Top

Klaytn and Incheon City’s NFT Project Set to Bring Blockchain to the Public

Web3 & Enterprise·October 24, 2023, 7:51 AM

The Klaytn Foundation, a non-profit organization backed by South Korean messaging giant Kakao, announced Tuesday (local time) a new collaboration with the city of Incheon to launch the Incheon Universe NFT project on the Klaytn blockchain.
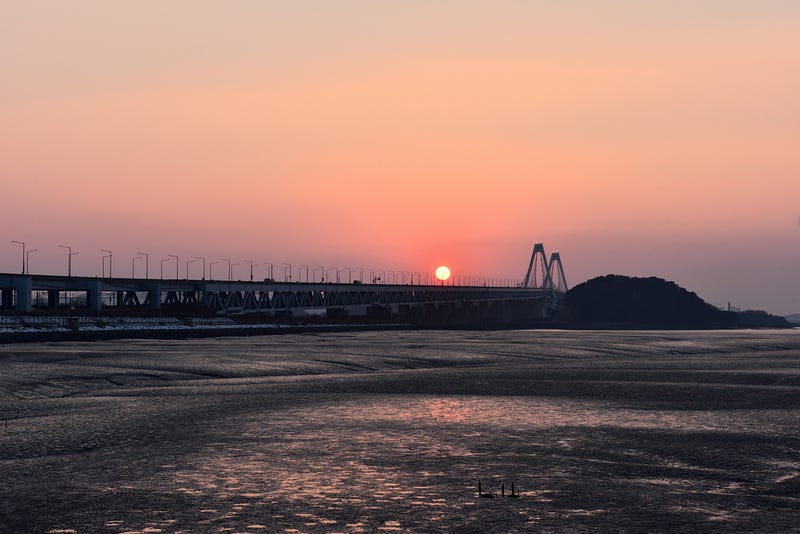
Photo by joon young, Park on Pexels


NFTs representing seals and lighthouses

Set to be issued on Wednesday, these non-fungible tokens (NFTs) are based on Incheon Heroes characters, which draw inspiration from seals, one of the country’s endangered species, and lighthouses, seen as guardians of the sea. The Incheon Universe NFT project will harness the online metaverse and decentralized autonomous organizations (DAOs) to create a space where residents can connect, sharing their preferences and values. Additionally, the project seeks to enhance the pride of those living in Incheon.

The Incheon Universe NFT project is set to kick off on October 25, marking the inaugural minting of Incheon Heroes NFTs on the Klaytn blockchain. These NFTs will also serve as membership passes. For this initiative, the Klaytn Foundation has been offering technical assistance and advice.


Fee delegation feature

The foundation and Incheon City plan to leverage the fee delegation feature to remove the burden of a small transaction fee typically associated with NFT minting. This move is intended to lower the entry barrier for individuals unfamiliar with participating in blockchain projects. Incheon is also orchestrating in-person events catered to NFT holders. The city is also in discussions with the Klaytn Foundation, mobile carrier LG Uplus, media commerce entity Lotte Homeshopping, marketing solutions provider Daehong Communications, and others for more collaborative endeavors.

Commenting on the collaboration, Lee Se-woong, Brand Manager of Incheon City, emphasized how both parties benefit from the partnership. While the Klaytn Foundation has been at the forefront of collaborations in the global blockchain scene, leading various projects, Incheon is positioning itself for new initiatives in the Web3 era. Lee sees this partnership as a major boost for the city.

Seo Sang-min, the Klaytn Foundation’s Representative Director, mentioned that the foundation is committed to working closely with the city to ensure the success of the Incheon Universe NFT project as a city-driven blockchain initiative. He emphasized that Klaytn aims to help more people experience firsthand the benefits of Web3 technology.

Incheon has been at the forefront of driving blockchain initiatives. Among its recent undertakings is the Global Blockchain Incheon Conference (GBIC 2023), which is slated for October 30 to 31. The event will highlight presentations from renowned speakers representing blockchain entities like Polygon Labs, Crypto.com, and the Astar Foundation.
More to Read
View All
Policy & Regulation·

Sep 15, 2023

Singapore’s Regulator Imposes 9-Year Ban on 3AC Founders

Singapore’s Regulator Imposes 9-Year Ban on 3AC FoundersSingapore’s central bank and financial regulator, the Monetary Authority of Singapore (MAS), has handed down a nine-year prohibition order to Kyle Davies and Su Zhu, co-founders of the failed crypto hedge fund Three Arrows Capital (3AC).Photo by Swapnil Bapat on UnsplashSevere restrictionsThe penalty relates to alleged violations of the city-state’s securities laws. The prohibition order came into effect on Wednesday, carrying severe restrictions for Davies and Zhu.During this nine-year period, Davies and Zhu are prohibited from engaging in any regulated activities in Singapore. They are also barred from managing, serving as directors, or holding substantial shares in any capital market services business within the territory of Singapore.Loo Siew Yee, the Assistant Managing Director of Policy, Payments, and Financial Crime at MAS, emphasized the seriousness of the violations in a statement released by the central bank on Thursday. Yee stated:“MAS takes a serious view of Mr. Zhu’s and Mr. Davies’ flagrant disregard of MAS’ regulatory requirements and dereliction of their directors’ duties.” She further asserted that MAS would take action against senior managers who engage in such misconduct.Securities law violationsMAS’s decision to impose these sanctions on the 3AC co-founders was based on its findings of further securities law violations during investigations into 3AC and its founders. The regulatory authority accused Davies and Zhu of failing to inform MAS when 3AC hired a new business representative, providing false information to the regulator, and neglecting to establish an appropriate risk management framework.3AC’s troubles stemmed from the crypto market crash that occurred last year, triggered by the Terra ecosystem’s collapse. The hedge fund’s leveraged crypto positions exposed it to billions in loan defaults, resulting in significant financial losses. Its lack of risk management had a cascading effect in crypto. Lenders like Celsius and BlockFi had exposure to 3AC, leading to further collapses later in 2022 as a consequence.3AC’s creditors claim that the firm owes as much as $3.5 billion, and liquidators are now seeking to recover approximately $1.3 billion from Zhu and Davies, who allegedly incurred the debt when the firm was already insolvent.Regulatory reprimandsThis action by MAS follows last June’s reprimand of 3AC, which occurred just before the hedge fund filed for bankruptcy amid widely reported insolvency issues. At that time, MAS had criticized 3AC for providing false information, failing to report directorship changes involving Zhu and Davies, and exceeding the legal assets under management threshold.It’s just the latest reprimand the duo have received from a regulator this year, though. Zhu and Davies have been busy in trying to get another start-up off the ground. Earlier this year, they launched OPNX, a crypto bankruptcy claims trading platform. The venture is based out of Dubai, and the firm reported in April that it had gotten significant VC backing.Many of those that the company claimed were backing the venture disassociated themselves from those claims. The following month, the Dubai regulator, the Virtual Assets Regulatory Authority (VARA), reprimanded the OPNX founders, having issued an investor alert relative to the firm a few weeks prior to that. VARA's complaint was that the business had been operating without having acquired the appropriate licensing.

news
Web3 & Enterprise·

Apr 30, 2025

Circle & local institutions advance stablecoin projects in Abu Dhabi

It’s proving to be a significant week for the further development of stablecoins in the United Arab Emirates (UAE) with leading U.S. dollar-backed stablecoin issuer Circle achieving in-principle licensing approval in Abu Dhabi, while a group of Abu Dhabi-based institutions have announced plans to launch a UAE dirham-pegged stablecoin.Photo by Yan Ma on UnsplashRegulatory licensingIn a press release published on April 29 Circle outlined that it had received in-principle approval to operate as a money services provider from the Financial Services Regulatory Authority (FSRA), the regulator for projects operating out of the Abu Dhabi Global Market (ADGM). ADGM is a free zone located within the UAE capital that has established its own regulatory framework for virtual asset-based businesses. The in-principle licensing award puts the company on a firm path towards the acquisition of a full Financial Services Permission (FSP) license. Circle Co-Founder Jeremy Allaire said that this in-principle licensing “advances our strategy to establish deep roots in markets embracing the onchain economy, creating new pathways for investment and innovation in the region.” On X, Ian Ballina, founder and CEO of Token Metrics, said that the licensing milestone signaled more global momentum for crypto adoption. Ballina pointed out that Circle’s USDC stablecoin is gaining traction as a result of the company’s strategy of partnering with local tech innovators. In addition, Circle announced a collaboration with Hub71, an Abu Dhabi-based global tech ecosystem. The objective of the partnership is to strengthen innovation within the digital assets space, with Circle joining Hub71’s digital assets ecosystem to offer expertise to a community of more than 500 tech startups and venture capital firms. Dirham stablecoin launchIn a separate development, ADQ, an Abu Dhabi-headquartered sovereign wealth fund, announced that it had joined with local partners to launch a UAE dirham-pegged stablecoin.  In its efforts to launch the stablecoin, ADQ has partnered with First Abu Dhabi Bank (FAB), the UAE’s largest bank, and conglomerate International Holding Company (IHC). The trio envisage that the stablecoin will be regulated by the UAE’s central bank and will be used “by citizens and consumers, businesses and institutions.” Once regulatory approval has been granted, the stablecoin will be hosted on the ADI blockchain, a network which was established by the Abu Dhabi-based non-profit ADI Foundation. ADQ CEO H.E. Mohamed Hassan Alsuwaidi described the launch of the stablecoin as “a pivotal step in our commitment to strengthening the UAE’s digital infrastructure ecosystem.” He added that the stablecoin will provide a secure, efficient and scalable solution for market participants as the UAE progresses towards an increasingly digital and connected economy. FAB CEO Hana Al Rostamani suggested that the new stablecoin would make a significant impact, with the potential to “revolutionize the use of trusted blockchain payments for UAE consumers and businesses.” Last December, the FSRA approved leading U.S. dollar stablecoin Tether (USDT) as an accepted virtual asset (AVA). Some weeks prior to that approval, Tether outlined that it planned to launch a dirham-backed stablecoin in collaboration with local partners. In October the country’s central bank issued in-principle approval to the promoters of another dirham-backed stablecoin, AE Coin.

news
Policy & Regulation·

Oct 06, 2023

Further JPEX Controversy Due to DAO Plan

Further JPEX Controversy Due to DAO PlanDubai-headquartered crypto exchange JPEX, which has recently found itself at the center of controversy in Hong Kong, has moved forward with a plan to transition the platform into a decentralized autonomous organization (DAO).Photo by Clint Adair on UnsplashDisputed voting outcomeThe firm’s management envisages converting user assets into dividend shares, with an incentive to lock them up for two years. While the exchange claims that the majority of its users voted in favor of the plan, some users are alleging that their assets have been converted without their knowledge or consent.The company announced the outcome of its DAO Shareholder Dividend Scheme referendum on its website on Wednesday. According to JPEX, voting on the program concluded on September 28. The company alleges that 68% of users voted to support the proposed scheme.Asset conversionUnder this plan, users can convert their currently frozen assets into DAO Stakeholder dividends at a 1:1 ratio. JPEX also offers a repurchase option at 30% of the conversion price after one year and a 100% repurchase option after two years.In a prior announcement, JPEX stated that users who agreed to the scheme would receive dividends from the exchange through a new token listing, trading fees, and a distribution of JPEX Coin (JPC), the platform’s native token, in proportion to their shareholder dividends.The scheme seems to encourage users to keep their funds on the exchange, which has been grappling with liquidity issues. Previously, the exchange had taken to putting in place unreasonably high withdrawal fees to discourage users from attempting to withdraw their funds from the platform.Ongoing falloutThere has been ongoing fallout from the exchange businesses' difficulties over recent weeks. At first, a number of influencers who had promoted the exchange were arrested. Later, Hong Kong regulators suggested they were giving further scrutiny to crypto trading regulations in light of the scandal.Further arrests were made in connection with the exchange’s activities. Regulators have suggested that they would create a public listing of platforms that are actually regulated within the Chinese autonomous territory and the licensing status of those businesses. On Thursday the South China Morning Post (SCMP) reported that a further six people have been arrested in relation to the scandal, including the company’s CEO.In another report on Wednesday the SCMP had cited one platform user who maintained that her assets had already been converted to JPC tokens without her consent or prior knowledge. She and other users discovered that they could no longer withdraw their assets following JPEX’s announcement to proceed with the plan.“All of my [Tether] USDT and other cryptocurrencies are gone, all transferred to JPC,” she lamented, noting that her assets had been converted to JPC, a token with low liquidity and limited use cases. She expressed concern about the unknown price of JPC and the inability to withdraw, suggesting their assets had become worthless.On Wednesday, Hong Kong’s police and securities regulator jointly launched a crypto-focused task force aimed at combating illicit activities by cryptocurrency exchanges in the region.

news
Loading