Top

Hackers spirit away over $300M in Bitcoin from DMM Bitcoin

Markets·June 04, 2024, 3:28 AM

Japanese crypto exchange DMM Bitcoin announced on Friday that over $300 million worth of Bitcoin was stolen from its primary wallet, marking one of the digital asset industry's largest hacks in recent years.
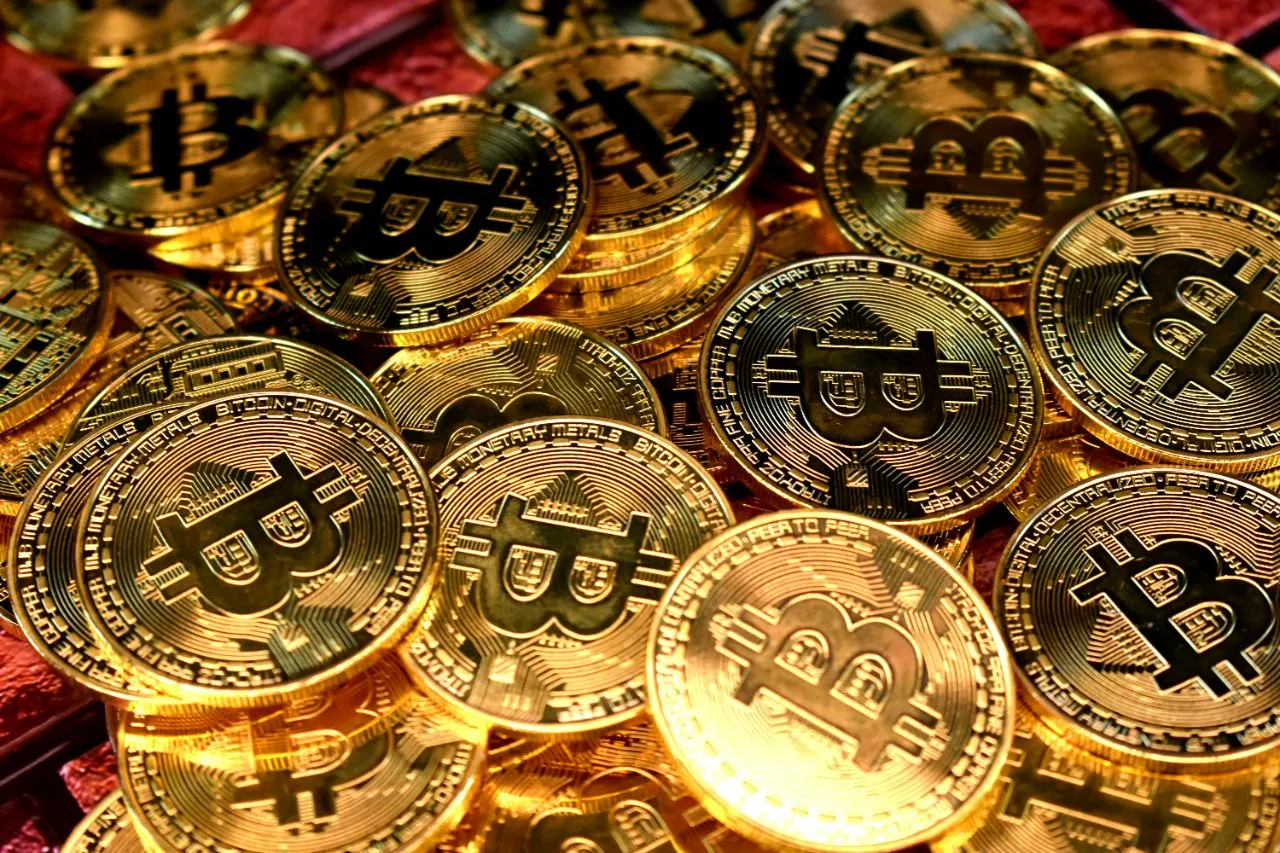
https://asset.coinness.com/en/news/eebe7e21c5cf8ed0475ba0d9f4e98d52.webp
Photo by Kanchanara on Unsplash

Hack confirmed without further detail

"At approximately 1:26 p.m. on Friday, May 31, 2024, we detected an unauthorized leak of bitcoin from our wallet," the company stated, based on an English translation of its original statement in Japanese, which had been posted on the firm’s website. DMM Bitcoin is a subsidiary of DMM Group, which incorporates businesses covering a broad spectrum of activities including solar energy, gaming, 3D printers, FX, e-books and software.


The company has, as yet, not provided any further detail relative to the manner in which the hack occurred. Notwithstanding that, DMM Bitcoin did confirm that measures have been taken to prevent any repeat of the hack. Furthermore, the company outlined that a full investigation into the hack is ongoing right now.


Buy orders and leverage trades suspended

The company has moved to reassure platform users that their digital assets are fully guaranteed. It stated:


"Please rest assured that all of your bitcoin deposits will be fully guaranteed, as we will procure the equivalent amount of BTC that was leaked with support from our group companies." 


The exchange has taken the decision to temporarily suspend a number of activities, including spot trading buy orders and the opening of leveraged trading positions. A temporary halt has been imposed on crypto withdrawals while Japanese yen withdrawals are permitted, albeit that the exchange suggests that service users may experience delays.


Blockchain security sector response

In light of the hack, a number of well-known blockchain security firms have been giving the matter their attention. Beosin, a blockchain security specialist, outlined that it is continuing to monitor the wallet addresses implicated in the hack, with a view towards tracing any further movement of the funds.


Meanwhile, blockchain analysis firm Arkham Intelligence has offered a 1,000 ARKM token bounty to anyone who may provide information leading to the identification of the perpetrators of the hack. Blockchain analysis firm Chainalysis described the hack as “the 7th largest crypto hack ever.” The company has labeled the stolen funds within its products.


Broader industry implications and historical context

This hack is a significant blow to the industry, given that a hack on this scale has not occurred thus far in 2024 or at any point during 2023.


The crypto industry has faced numerous significant breaches in the past. In 2022, a series of large-scale exploits targeted layer-1 blockchains, crypto exchanges and DeFi protocols. The largest hack amongst them implicated the BNB Chain (formerly Binance Smart Chain), which resulted in the loss of $566 million worth of BNB.


The latest hack is second only (within Japan) in size relative to the 2018 hack of Coincheck, one of the country’s largest exchanges, when over $550 million worth of XEM was stolen. Japan was also host to the most infamous Bitcoin hack, that of the Mt. Gox exchange, whose bankruptcy administrators moved $9 billion worth of its remaining Bitcoin holdings on the blockchain in recent days for the first time in many years.
 

More to Read
View All
Policy & Regulation·

May 28, 2025

Pakistan appoints crypto advisor to PM & allocates 2K MW to Bitcoin mining

Recent weeks have seen a positive policy shift in Pakistan with regard to digital assets and blockchain and that initiative has gathered further momentum with the appointment of a special assistant on blockchain and crypto to the Pakistani prime minister and the allocation of 2,000 MW of surplus electricity to Bitcoin mining and AI data centers.Photo by Abuzar Xheikh on UnsplashOn May 26, the Pakistan Observer, an English language daily newspaper, reported that Bilal bin Saqib has been appointed to serve as a special assistant on blockchain and crypto matters to Pakistani Prime Minister Shehbaz Sharif. Forbes ‘30 under 30’ social entrepreneurIn this role, Saqib assumes the status of a minister of state under Rule 4(6) of the Rules of Business, 1973, with the appointment effective immediately. Saqib had been featured by Forbes through its “30 under 30” list of social entrepreneurs in Asia in 2020. He is the founder of Tayaba.org, a non-governmental organization (NGO) focused on the provision of clean drinking water to vulnerable communities in Pakistan. Saqib came to prominence in the crypto sector earlier this year when he was appointed CEO of the newly formed Pakistan Crypto Council (PCC), an agency established to promote blockchain technology and digital assets within the South Asian country. In April he was added by World Liberty Financial, a crypto project connected with the family of U.S. President Donald Trump, as an advisor. Earlier this month, Pakistan’s Ministry of Finance gave the go-ahead for the establishment of the Pakistan Digital Assets Authority (PDAA), a body that will be responsible for the implementation of regulations governing the crypto and blockchain sector.  Utilizing surplus energyAt the time, one area of focus that had been highlighted in the announcement of the establishment of the PDAA was a desire to make better use of Pakistan’s surplus energy. The country runs an annual average surplus of 4,000 megawatts. A report by 24 Digital on May 25 indicated that action has already been taken in this regard. It outlined that Pakistan has allocated 2,000 megawatts of surplus electricity for the exclusive use of operators of AI data centers and Bitcoin mining facilities.  This plan is being rolled out in phases. The first phase makes surplus energy available to these operators. Phase 2 will focus on enabling crypto mining operators to avail of renewable energy to power their facilities, in an effort to develop the sector in Pakistan in an environmentally responsible manner. According to the Ministry of Finance, interest has already been expressed by international operators in the crypto mining and AI data center sectors. A number of international firms are understood to have visited the country in an effort to explore potential collaboration opportunities.  Earlier this month, Saqib claimed on social media that Pakistan “is moving at crypto speed.” He made the case that the country is a breeding ground for crypto innovation, citing the opportunity to exploit surplus electricity via crypto mining and the potential for crypto adoption given a $36 billion remittance market, millions of unbanked citizens and 64% of the population under 30.

news
Web3 & Enterprise·

Aug 08, 2023

OPNX Makes a Play for Struggling Crypto Lender Hodlnaut

OPNX Makes a Play for Struggling Crypto Lender HodlnautIn a strategic move OPNX, the crypto claims trading platform associated with the founders of failed Singaporean crypto hedge fund Three Arrows Capital (3AC), is eyeing the acquisition of Hodlnaut, a beleaguered crypto lender currently undergoing court-supervised restructuring in Singapore.Photo by Meriç Dağlı on UnsplashCompelling offerThat’s according to a person familiar with the matter cited by Bloomberg News on Sunday, together with a term sheet seen by Bloomberg. It’s understood that OPNX has presented a compelling offer to infuse Hodlnaut with a much-needed capital injection of approximately $30 million worth of FLEX digital tokens.These tokens are closely tied to CoinFLEX, a trading platform that ran into difficulty in 2022, co-founded by Mark Lamb and Sudhu Arumugam. The Seychelles-based company rebranded and relaunched as OPNX earlier this year with the 3AC founders on board. The FLEX token holds a current market valuation of around $647 million, according to CoinGecko data.Partial creditor payoutThe OPNX proposal aims to fund a partial creditor payout to facilitate the resolution of pending claims. This proposal comes on the heels of efforts by Hodlnaut’s directors to reach out directly to its users, a move that was met with objections by the interim judicial managers overseeing Hodlnaut’s restructuring. A letter dated July 29 from the administrators confirms this development.Under the terms of the deal outlined in a term sheet, OPNX’s capital injection through FLEX tokens would translate into a 75% ownership stake in Hodlnaut. The restructuring plan, if approved by creditors, would see these creditors receiving 30% of their claims in FLEX and other tokens. Alternatively, they would be entitled to a pro-rata payment of up to 95% of the total available corporate assets, whichever is more favorable to them.Hodlnaut, headquartered in Singapore with operations also in Hong Kong, got caught up in crypto market turbulence, leading to a suspension of withdrawals a year ago. Subsequently, it embarked on a court-monitored restructuring journey in Singapore. Neither Hodlnaut nor its judicial managers have provided immediate comments on the OPNX bid.The founders of Hodlnaut, Simon Lee and Zhu Juntao, had earlier proposed a business sale as a preferable alternative to liquidation. This proposal aimed to provide better outcomes for creditors, who had initially expressed preference for liquidation over a proposed restructuring plan earlier in the year.OPNX reprimandThe journey of both OPNX and Hodlnaut is also marked by legal and regulatory challenges. In April, authorities in Dubai reprimanded Su Zhu, Kyle Davies, Mark Lamb, OPNX’s CEO Leslie Lamb, and Sudhu Arumugam for operating and promoting OPNX without the required local license. Meanwhile, the liquidators of 3AC have alleged a lack of cooperation by Zhu and Davies, as they seek to recover $1.3 billion from the duo, reflecting the losses preceding the fund’s downfall.The 3AC founders recently claimed that they would donate OPNX profits to 3AC creditors. However, Kyle Davies is fighting the efforts of the 3AC liquidator to reclaim funds from the founders.

news
Policy & Regulation·

Dec 16, 2025

Korea to seek central bank input only for major stablecoins

South Korean lawmakers are moving to seize control of the nation’s stalled second phase of digital asset legislation, aiming to bypass months of interagency gridlock and introduce a comprehensive regulatory framework by January. The legislative acceleration comes as Seoul races to align with global standards following the implementation of the U.S. GENIUS Act in July, a shift that has intensified pressure on local regulators to formalize oversight of the crypto sector. According to a report from the Maeil Business Newspaper, the ruling Democratic Party of Korea (DPK) plans to introduce the Digital Asset Basic Act as a lawmaker-sponsored bill rather than wait for a government submission. The procedural move is intended to ensure that formal deliberations can begin during the February provisional session. Lawmaker Kang Jun-hyeon, a DPK member of the National Policy Committee, told reporters on Dec. 11 that relying on the government’s timeline would jeopardize passage of the bill in the first half of next year. Kang cited points of disagreement among the parliament, the government, and industry stakeholders. Among the authorities, in particular, a standoff between the Bank of Korea (BOK) and the Financial Services Commission (FSC) over monetary policy and issuance authority has been a key source of delay.Photo by Lauren Seo on UnsplashDraft sets ‘major’ stablecoin requirementsAt the heart of the legislation is a new classification system for stablecoins. The government delivered its draft for the Digital Asset Basic Act to DPK’s Digital Asset Task Force, outlining its intention to classify won-denominated stablecoins exceeding a certain issuance threshold as “major digital payment tokens.” According to Blockmedia, citing sources familiar with the closed-door briefing to the task force, these assets would fall under a rigorous oversight framework developed in consultation with the central bank. Under the draft rules, issuers would be required to maintain 100% reserves, prohibited from making interest payments to holders, and obliged to submit detailed issuance plans to the FSC. Foreign-issued stablecoins would only be permitted to circulate domestically if the issuer establishes a local branch. Although the government ultimately submitted its draft to the DPK, the delivery was delayed by two days, missing the Dec. 10 deadline set by the party. Officials attributed the postponement to unresolved interagency disagreements. The central bank had argued that any issuance should require unanimous approval from all relevant agencies, including itself, but the government agreed to involve the bank only when a token is designated as “major.” The Bank of Korea continues to advocate for a bank-led consortium issuance model, highlighting the coordination challenges that have complicated the bill’s preparation. Supply thresholds emerge as fault lineCritics warn that the proposed regulations could inadvertently tilt the market against domestic innovation. Analysts argue that if the threshold for the "major" designation is set too low, new won-based issuers may face compliance costs that could undermine their business viability before they reach meaningful scale. They added that setting the bar for entrenched dollar-backed issuers such as USDT and USDC is also complex, given that their combined global issuance already exceeds $250 billion. Market participants said concerns about triggering the “major” designation could prompt Korean issuers to cap supply to avoid heightened scrutiny, effectively stifling growth from the outset. Despite these concerns, political will to close the policy vacuum is hardening. The DPK intends to move the legislation forward on its own timetable, incorporating the government’s input but steering the process through parliament. Lawmaker Kang emphasized that while numerous issues remain, the task force aims to narrow the debate to a few essential questions before the bill’s planned introduction in January. Industry representatives have largely welcomed the clearer timeline, viewing the move as a necessary step to reduce uncertainty as the global crypto sector comes under more formal regulatory oversight. 

news
Loading