Top

Japanese cabinet approves crypto tax reform

Policy & Regulation·December 26, 2023, 12:41 AM

The Japanese government has green-lit an amendment to its fiscal 2024 tax reform plan, specifically targeting the taxation of companies holding third-party-issued cryptocurrencies.
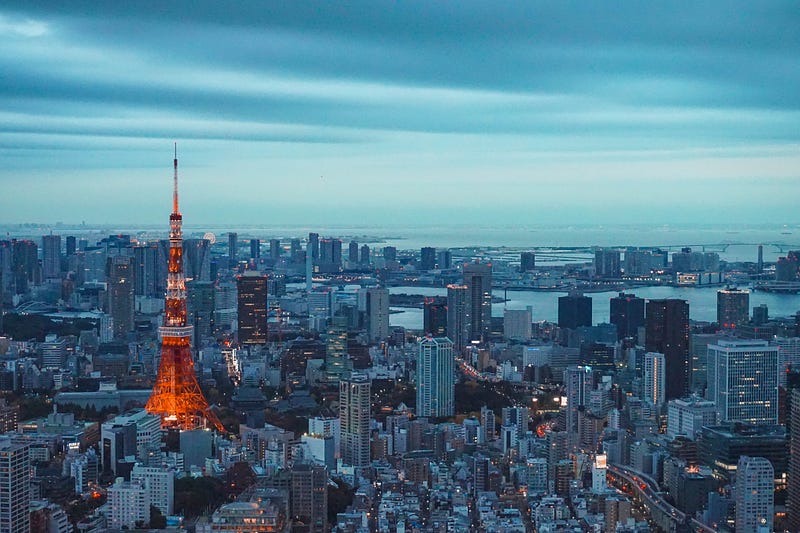
Photo by Louie Martinez on Unsplash


Introducing tax exemption

According to local news sources, this amendment brings about a crucial change by exempting such companies from the year-end mark-to-market valuation tax.

The Fiscal Year 2024 Tax Reform Outline, now approved by the Japanese cabinet, marks a departure from the previous tax regime. Under the new framework, companies holding crypto assets will no longer be subjected to mark-to-market valuation at the end of the fiscal year. Instead, they will be taxed solely on the actual profits realized from the sale of virtual currencies and tokens.


Alleviating the tax burden

The primary motivation behind this amendment is to alleviate the tax burden on corporations engaged in the holding and operation of crypto assets. Previously, corporations holding third-party-issued cryptocurrencies were required to record profits or losses based on the difference between market value and book value at the end of the fiscal year. The new reform, however, exempts assets assumed to be held continuously from this mark-to-market valuation.

News of moves to implement such reform emerged at the beginning of December. At the time, a report by Nikkei Asia suggested that Japanese lawmakers were working towards addressing issues related to crypto taxation. Japanese regulator, the Financial Services Agency (FSA) had first proposed such changes to the tax code via a 16-page submission on Aug. 31.


Signaling investor-friendly approach

This policy shift aligns the taxation of companies with the tax system applicable to individual investors, signaling a more investor-friendly approach. Lawmakers from the Liberal Democratic Party and their coalition partner Komeito had reportedly considered a proposal to exempt corporations from taxes on unrealized crypto gains. This move is seen as Japan’s effort to boost liquidity in the market, putting it in line with other Asian regions striving to become prominent centers of crypto activity.

The amendment, influenced by the Japan Cryptoasset Business Association’s (JCBA) call for tax reform, is anticipated to stimulate the growth of local startup businesses utilizing blockchain technology and attract international projects to the Japanese market.

The proposal is set to be presented at the regular session of the National Diet (Japan’s national legislature) in January of the upcoming year, where it will require approval from both the House of Representatives and the House of Councilors.

Notably, the Fiscal Year 2024 Tax Reform Outline encompasses a broader spectrum of economic policies, including a plan to reduce income tax and resident tax by 40,000 yen per person from June 2024 onwards.

News of the crypto tax reform has been well-received by most industry commentators and market participants. Daiki Moriyama, Director of Singapore-based gaming blockchain project Oasys, reacted positively to the development. He told The Block:

“The fact that the Japanese government has demonstrated its willingness to grow Web3 business by enacting tax reform for the second year in a row is extremely important to all Web3 business stakeholders around the world.”

More to Read
View All
Web3 & Enterprise·

Aug 18, 2023

One Store’s App Market to Support Polygon-Based dApps

One Store’s App Market to Support Polygon-Based dAppsSouth Korean native app market One Store said Friday that it has signed a memorandum of understanding (MOU) with Polygon Labs, the operator of the Polygon blockchain network, to provide robust support for Web3 games and decentralized applications (dApps) as part of its upcoming global service expansion.The signing ceremony for the MOU took place on Thursday at One Store’s headquarters in Seongnam, Gyeonggi Province. Peter Chun, CEO of One Store, and Marc Boiron, CEO of Polygon Labs, were in attendance.Polygon is a layer 2 scaling solution for Ethereum, with numerous domestic and international gaming companies already partaking in the Polygon ecosystem for a variety of purposes, such as Web3 game development and technological collaborations.Elevating user experienceThis new partnership is part of One Store’s efforts to offer enhanced choices for mobile users worldwide, setting its sights on overseas expansion and the creation of a global platform. With a focus on supporting Web3 games, the platform aims to cater to the blockchain gaming and app user base on an international scale, thus contributing to the expansion of the Web3 gaming ecosystem.Photo by Jonas Leupe on UnsplashAccording to the agreement, One Store will support marketing for Web3 games that have onboarded the Polygon platform, while Polygon Labs will encourage game developers that use its platform to enter One Store’s global market.“Through the upcoming global One Store platform, we will connect with users worldwide who are eagerly anticipating Web3 games and apps,” CEO Chun said.This marks a significant step towards the realization of a vibrant Web3 gaming and dApp landscape on a global scale. The collaboration is expected to bring about new opportunities and experiences for users seeking innovative and engaging digital content.Polygon’s collaboration with Korean industry leadersPolygon Labs has been teaming up with other Korean companies as well, including the telecommunications giant SK Telecom, in efforts to further nurture the ever-growing Web3 ecosystem.

news
Policy & Regulation·

Sep 24, 2023

Bybit Suspends UK Services Due to New Marketing Regulations

Bybit Suspends UK Services Due to New Marketing RegulationsDubai-based crypto exchange Bybit has taken the proactive decision to suspend services in the UK market ahead of the impending implementation of new cryptocurrency marketing regulations by the Financial Conduct Authority (FCA).Photo by Nick Fewings on UnsplashNew marketing rulesThe FCA is set to enforce these rules starting next month, marking a significant shift in the regulatory landscape for crypto businesses operating in the United Kingdom. In an official announcement published on its website on Friday, Bybit stated: “In light of the UK Financial Conduct Authority’s introduction of new rules regarding marketing and communications by crypto businesses as outlined in the June 2023 Policy Statement (PS23/6) entitled ‘Financial Promotion Rules for Crypto assets,’ Bybit has made a choice to embrace the regulation proactively and pause our services in this market.”Efforts to remainLast week, there had been speculation that the crypto exchange platform would be exiting the UK market. However, Bybit responded on September 14, stating that it intended to maintain its presence in the UK over the long term.Clearly these new rules are proving to be an insurmountable challenge for the exchange platform, given its more recent decision to pause its services. The new rules aim to introduce a cooling-off period for first-time investors, with the ultimate goal of enhancing the transparency and accuracy of crypto product marketing.Their implementation has drawn criticism from within the industry. On Thursday, Nic Carter, Co-Founder of blockchain data aggregator Coinmetrics.io and Partner at Web3-focused venture capital firm Castle Island Ventures, shared his thoughts on the new regulations via X (formerly Twitter): “I have a hard time taking the UK seriously as a domicile for crypto companies based on their completely ludicrous advertising law — clown country.”Withdrawal timelineBybit has outlined a timeline for its withdrawal from the UK market. Starting from October 1, the exchange will no longer accept new user account applications from UK residents.Subsequently, on October 8, coinciding with the enforcement of the new regulations, existing UK users will no longer be able to “make any new deposits, create new contracts, or increase any of their existing positions for all products and services.” However, users will retain the ability to reduce or close their positions and withdraw their funds from the platform.Bybit has set a final deadline of January 8, 2024, for UK customers to manage and wind down their remaining positions. Any positions left open after this date will be automatically liquidated, with the resulting funds made available for withdrawal.While the duration of Bybit’s suspension in the UK remains uncertain, the exchange has expressed its commitment to aligning with UK regulatory requirements in the future. Bybit stated: “The suspension will allow the company to focus its efforts and resources on being able to best meet the regulations outlined by the UK authorities in the future.”Bybit is not the only crypto exchange affected by the UK’s regulatory changes. Other major platforms, including OKX and Binance, are reassessing their strategies in response to the FCA’s stringent guidelines. The new rules have broad implications, with even having a website accessible to UK customers potentially being considered a promotional activity.

news
Policy & Regulation·

Apr 11, 2023

India Looks to Boost CBDC With 1 Million Users in 3 Months

India Looks to Boost CBDC With 1 Million Users in 3 MonthsThe project team responsible for India’s retail central bank digital currency (CBDC) is aiming to increase its user base to one million users, while also prioritizing the challenge of creating an offline version.©Pexels/Sohel PatelAlthough the Reserve Bank of India (RBI), India’s central bank, publicly stated in March that they were aiming for 500,000 users by July, they are privately looking to double that amount. According to sources familiar with the matter cited by CoinDesk, the architects behind the centralized digital currency are confident that India’s population, being the world’s largest, will enable them to reach one million users easily. Tentatively the project team is aiming to achieve this within three months.Retail and Wholesale CBDCsThe RBI is currently conducting both retail and wholesale CBDC pilot programs. The retail CBDC pilot is active in at least 15 cities, with more than 13 banks participating. The digital rupee pilot began on December 1, 2022, and has seen over 100,000 customers participate in the four months since.India’s digital rupee gained significant attention at a recent meeting of the Group of 20 (G-20), which was hosted by India in Bengaluru, according to RBI Governor Shaktikanta Das. The central bank received positive feedback, with praise received for the design of the CBDC.Multiple challengesThe RBI initiated a Hackathon in 2023 to find solutions to some of the challenges around retail CBDC, including improving scalability, increasing transactions per second, and enabling offline transactions. However, achieving all three technical objectives at once is nearly impossible at present. Experts believe that it is only possible to achieve two out of the three objectives, but the hope is that technological innovation will address this in the future.Offline transactionsFacilitating offline transactions is crucial to improve financial inclusion in emerging economies such as India. The RBI is testing various methods to enable offline transactions, including wearables, debit and credit cards, Bluetooth technology, and smartphones. The central bank is also looking to address the risk of double-spending.More than 50 proposals were submitted to the RBI to solve the problem of offline transactions. The RBI has also been interacting with private companies to consider solutions to improving scalability, even though no partnership has been initiated with any prominent blockchain-related entities.News of India’s ambitious CBDC project fast-tracking has led some to speculate as to what technology lies behind it. Some have suggested Ripple as a possible partner but the suggestion is entirely speculative at this point.The RBI has not announced a timeline for rolling out a full-scale retail CBDC but has indicated previously that it was aiming for the end of the year. The development of a digital rupee has the potential to transform India’s economy by providing greater financial inclusion to its population, which is why the RBI is taking the time to ensure that the CBDC is as robust as possible.

news
Loading