Top

Solomon Islands partners with Soramitsu on CBDC pilot

Web3 & Enterprise·December 01, 2023, 2:54 AM

Central bank digital currency (CBDC) development has been ongoing globally at a brisk pace in 2023 and smaller nations, like the Solomon Islands with a population of over 700,000, are no exception when it comes to that process with the introduction of Bokolo Cash.
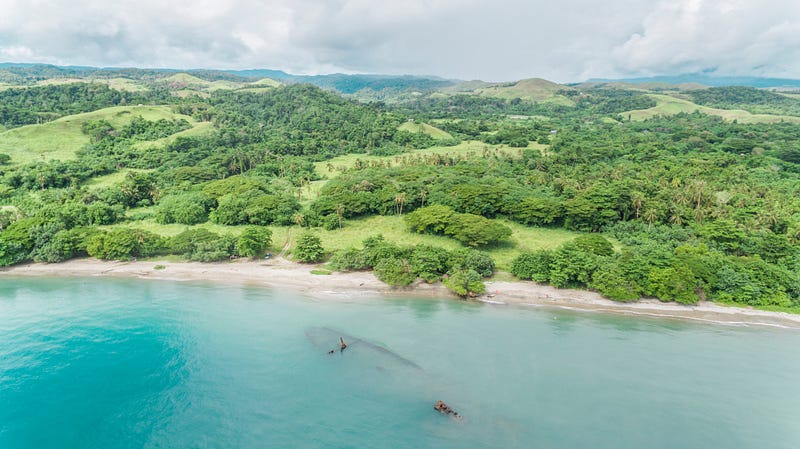
Photo by Gilly Tanabose on Unsplash


Introducing Bokolo Cash

Solomon Islands Central Bank (CBSI) has officially unveiled the proof-of-concept for its CBDC named Bokolo Cash, with support from Japanese blockchain firm Soramitsu. Bokolo Cash is pegged to the value of one Solomon Islands dollar.

The proof-of-concept pilot was launched on Tuesday by way of a keynote speech given by Manasseh Sogavare, the prime minister of the archipelago. In that speech, Sogavare highlighted that the CBDC would lead to reduced transaction costs for citizens and businesses. Users can rely on transactions to be both secure and transparent, given that the network will be blockchain-based.

The prime minister also articulated that the CBDC pilot project would be a catalyst for financial inclusion relative to the Island nation’s remotest communities.


Pilot scheme use cases

Participants in the project will have the opportunity to use it in various scenarios. From retail transactions in the capital city, Honiara, to person-to-person transfers, the CBDC aims to demonstrate its versatility. The proof-of-concept will also assess wholesale transfers between commercial banks, simulate cross-border payments and examine remittances. To ensure security and compliance, users will undergo a “two-step” Know Your Customer (KYC) verification process, as outlined by Soramitsu.

Operating on a customized blockchain based on Hyperledger’s Iroha, Bokolo Cash is designed for local use. However, it will also integrate with Soramitsu’s public Sora blockchain. This connectivity will enable users to engage in transfers using QR codes and the self-custody Fearless Wallet, a creation of Soramitsu.


Legislative change

Although the project commenced at the beginning of November, the official announcement was made earlier this week. The legislation required to enable the CBSI to issue the CBDC — CBSI (Amendment) Act 2023 — was enacted on Nov. 3.

The Solomon Islands, a collection of over 900 islands situated west of Papua New Guinea, now joins a group of island nations, including the Marshall Islands and Mauritius, actively experimenting with CBDC. Palau collaborated with Ripple Labs back in July to introduce the Palau Stablecoin (PSC). Interestingly, Tonga has contemplated adopting Bitcoin as legal tender, while Vanuatu hosts Satoshi Island, known for its Bitcoin-friendly environment. Meanwhile, Eastern Caribbean countries have already implemented an official CBDC called DCash.

Soramitsu has been active in collaborating with central banks relative to the introduction of CBDCs, particularly in Asia. It has played a key role in facilitating the issuance of the Cambodian Bakong and the Lao DLak in Laos. Furthermore, it has initiated a project for regional cross-border payments using the Bakong and a stablecoin.

In 2022, Soramitsu completed CBDC-related feasibility studies in conjunction with the relevant authorities in Vietnam and the Philippines. The Japanese fintech company has also participated with the Asian Development Bank and Tokyo-based global information technology solutions firm Fujitsu on a Web3 development project.
More to Read
View All
Policy & Regulation·

Mar 05, 2024

South Korea investigates Worldcoin for its personal data collection

On Thursday, South Korea’s Personal Information Protection Committee (PIPC) launched an investigation into Worldcoin’s personal data collection, processing and potential overseas transfer of sensitive personal data, the PIPC announced today via its official website. This comes after a number of complaints were filed against Worldcoin for its data collection practices.  Sam Altman’s crypto project Worldcoin gathers people’s personal data who signed up to have their irises scanned by “orbs” devices, which are currently installed in about 10 locations in Korea, including Yeouido, Pangyo and Apgujeong. The project started with the aim of distributing universal basic income to people whose jobs will be potentially replaced by artificial general intelligence (AGI) in the future. Photo by Colin Lloyd on UnsplashThe PIPC said the regulators will examine if any local privacy law has been violated by Worldcoin, and take further action in line with the Personal Information Protection Act. Following the launch of the investigation on Feb. 29, Worldcoin has withdrawn six orbs devices in Korea and stopped accepting new members. It has also suspended the distribution of the Worldcoin token (WLD) to members who have already signed up, media outlet Chosun Biz reported.  Free crypto tokens in exchange for personal data For individuals who have their irises scanned, Worldcoin rewards three WLD tokens every two weeks, which are worth approximately $22.5 (KRW 30,000) at the time of writing. The price of WLD has soared by nearly ten-fold from about KRW 1,300 last year to over KRW 13,000 today, according to the data from the local crypto exchange Bithumb. This price surge followed OpenAI’s launch of a text-to-video AI tool, Sora. The current circulating supply of WLD stands at around 100 million tokens. According to Worldcoin’s white paper, the WLD’s total supply cap will remain fixed at 10 billion tokens during the first 15 years following its launch.  The data collected from the eyeball scanning is shared on the Worldcoin blockchain, which is protected by the zero-knowledge proof technology that prevents the data from being tracked or shared with other applications. The personal data remaining in the orbs devices is deleted.  Ongoing overseas investigation on Worldcoin South Korea is not the only country that is examining Worldcoin’s personal data collection practices. The project’s processing of information has raised concerns in other jurisdictions as well, including the U.K., France, Argentina and Kenya. In the U.S., the issuance of WLD tokens has been banned by the country’s authority. 

news
Policy & Regulation·

May 26, 2023

Silence From Multichain’s Chinese Developers Stokes Fear

Silence From Multichain’s Chinese Developers Stokes FearA prolonged silence from the project leadership behind Multichain, a cross-chain routing network, is causing growing concern among the users of the cross-chain protocol. The network currently holds $1.5 billion in total value locked (TVL).The protocol has experienced five days of stuck transactions, and multiple cross-chain bridge pathways, including Kava, zkSync, and Polygon zkEVM are still offline. Initially, the project’s China-based team attributed the issues to an upgrade that was being fixed. That explanation was changed recently to an ambiguous “force majeure,” leaving users with more questions than answers.Photo by Santiago Lacarta on UnsplashPossible arrests in ChinaAdding to the uncertainty are rumors circulating on Twitter that the core leadership team may have been arrested in China. Although the rumors remain unconfirmed, they have contributed to the growing sense of unease within the community. DJ Qian, one of the co-founders of Multichain who is no longer involved with the project, took to Twitter to share his attempts to seek clarification. Qian mentioned reaching out to Multichain CEO Zhaojun and founding partner Xu Guochang for technical assistance. When asked about Zhaojun’s availability, Qian stated that he was “not available yet.”Users and investors eagerly await updates and clarity from Multichain’s leadership team. However, the team’s lack of communication extends across various forms of social media. In group Telegram messages with the Multichain team, there have been no responses from Zhaojun, and direct messages through the same app have gone unanswered as well. This silence has left the community members puzzled, with little information to rely on.$MULTI price plummetsMeanwhile, the price of Multichain’s native token, $MULTI, has continued to decline. It currently stands at $4.37, representing a 20% decrease over the past 24 hours. The lack of communication and uncertainty surrounding the project have likely contributed to this downward trend in token price. Over the course of the past seven days, the token has decreased in price by 45%.In response to the situation, layer 1 blockchain project Conflux Network has taken precautionary measures by suspending Multichain’s co-mint privileges. This move prevents Multichain from minting tokens on the Conflux blockchain. The Conflux Network has also assured users that it will work with them in case any losses arise due to the ongoing issues.Flight to safetyOther projects and individuals have also reacted to the silence from Multichain’s team. Hong Kong-based HashKey Group, a crypto investment firm, has transferred $250,000 to crypto exchange Gate.io as a precautionary measure. Tron founder Justin Sun has withdrawn 470,000 of the $USDD stablecoin from the Multichain protocol. These actions reflect a growing concern among stakeholders, representing their efforts to mitigate potential risks associated with the uncertainty surrounding Multichain.Furthermore, the Fantom Foundation has withdrawn $2.4 million in liquidity of the protocol’s native $MULTI tokens from the decentralized exchange SushiSwap. It later tweeted out an update stating that the Fantom-Multichain bridge was operating as normal. These withdrawals signal a loss of confidence in Multichain and its native token, as stakeholders seek to protect their investments.As the silence persists, users and investors remain anxious for updates and clarifications from Multichain’s leadership team. The lack of communication and the circulating rumors have cast a shadow of uncertainty over the project, leaving stakeholders in a state of limbo.

news
Policy & Regulation·

Dec 24, 2025

Japan moves toward municipal blockchain bonds as crypto tax reforms face delays

The Japanese government is moving to modernize municipal finance through blockchain technology, though the timeline for much-anticipated cryptocurrency tax reforms appears to be drifting further into the future. Municipal bonds as security tokensAccording to a Dec. 23 Nikkei report cited by CoinDesk Japan, policymakers decided to begin preparing to issue local government bonds as security tokens. The government aims to submit the necessary legislation during the ordinary Diet session in 2026. Concrete measures, shaped by requests from local municipalities, are expected to be finalized ahead of next year. Advocates say that issuing bonds as blockchain-based security tokens would modernize local government finance by reducing friction in issuance and settlement and enabling real-time tracking of investor data.Photo by Luke Stackpoole on UnsplashCrypto tax reform seen as taking timeWhile the digitization of bonds progresses, the schedule for easing the tax burden on crypto investors is reportedly facing setbacks. CoinPost reported that, according to sources, the transition to a separate tax on crypto gains is now expected to take place in January 2028, a delay from the initially envisioned target of January 2027. The legislative groundwork is still slated for the 2026 Diet session, where amendments bringing crypto assets under the Financial Instruments and Exchange Act (FIEA) will be deliberated. However, the current cautious policy approach prioritizes investor protection and adjustments to the tax reporting framework, making a delay in implementation more likely. The proposed amendments address the steep tax liabilities currently faced by domestic investors. Under Japan’s current system, crypto gains are treated as miscellaneous income, taxed comprehensively with salary and other earnings at rates that can reach roughly 55% when including local taxes. The plan, which the ruling coalition has been coordinating, aims to align crypto taxation with that of stocks and forex trading. It would introduce a flat 20% separate tax rate and allow loss offsets and carryforwards of up to three years, bringing crypto closer to other financial assets. It would also ease tax filing by potentially adopting a framework similar to the designated accounts used in Japan’s securities market, reducing the reporting burden on digital asset investors. The slow pace of these regulatory changes has drawn criticism from the private sector. Tomoya Asakura, CEO of SBI Global Asset Management, a subsidiary of SBI Holdings, took to the social media platform X to voice concerns about the pace of reform. Asakura characterized the process as "extremely slow," warning that the lag places Japan behind jurisdictions such as the U.S., Asia, and the Middle East. He argued that continued delays would further impede domestic initiatives in Web3 and digital finance. Bybit to pull out next yearAmid this shifting regulatory landscape, foreign entities are adjusting their operations. Dubai-based crypto exchange Bybit, which is not registered with Japan’s Financial Services Agency, announced on Dec. 22 it will phase out services for Japanese users to remain compliant with local rules. The exchange has stopped onboarding Japanese residents or nationals since 12:00 p.m. UTC on Oct. 31, and accounts held by customers in Japan will be gradually restricted starting next year. 

news
Loading